The Best Rate Is Not Always the Best Advice
The lowest mortgage rate isn't always the best financial decision. When buying our new home, I received two appealing recommendations that didn't fit our broader financial plan. Here's why looking at the bigger picture matters more than evaluating financial products in isolation.
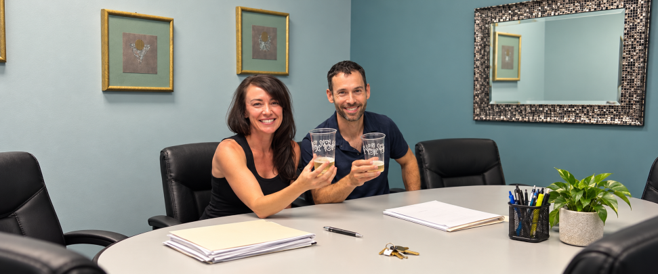
Kim and me celebrating the closing of our new home.
The photograph accompanying this article was taken at the closing of our new home.
Kim and I were genuinely happy. We had found a house that worked well for our family, successfully navigated the purchase and finally reached the point where we could celebrate.
But a great deal of work happened between finding the house and raising those glasses.
There were inspections, negotiations, documents, decisions about our existing home and, of course, the mortgage. One of the most important tasks was finding a mortgage that fit our specific plans - not simply the one with the most attractive advertised rate.
During that process, I received two recommendations that initially sounded very appealing.
One promised a significantly lower mortgage rate.
The other offered a mortgage discount and "more investment options."
Either recommendation might have been perfectly reasonable for someone else. But after I looked at how each one interacted with the rest of our financial plan, neither was right for us.
Good financial advice cannot be evaluated one product at a time.
The mortgage offer that sounded too good to pass up
As we prepared to purchase our new home, I explained our plan to a mortgage broker.
We expected to buy the new house before selling our existing home. Once the old house sold, we wanted to apply a substantial portion of the proceeds to the new mortgage and then, if permitted, recast the loan.
A mortgage recast generally works like this: You make a significant payment toward the principal of an existing mortgage. The lender then recalculates, or re-amortizes, your monthly principal-and-interest payment using the lower outstanding balance, the existing interest rate and the remaining term of the loan. Unlike refinancing, a recast generally does not replace the existing mortgage or change its interest rate. Its primary purpose is to reduce the required monthly payment after a large principal payment. Not every mortgage is eligible, and lenders may impose minimum-payment, timing and fee requirements.1
The broker knew that this was our plan.
She offered us a rate similar to the other rates we had received, but with an additional incentive: during the first year, our effective rate would be reduced by one percentage point.
A full percentage point sounded enormous.
I was excited.
During the conversation, I also asked about a fee of approximately $1,000. She told me not to worry about it because she would give us a credit. She explained that the lender would compensate her for originating the mortgage and that, because ours would be a relatively large loan, she could use part of that compensation to cover the fee.
I appreciated her transparency, but the conversation made me curious. If there was enough compensation available to absorb the fee, I wanted to understand the complete economics of the offer.
So I kept asking questions.
Eventually, I learned that under the promotional terms as they were explained to me, we would not be able to make the substantial additional principal payment we were planning during the one-year promotional period.
That changed everything.
I ran the numbers based on our expected home-sale proceeds and the timing of our planned principal payment. The value of applying that money to the mortgage - and avoiding interest on that portion of the balance - was substantially greater than the benefit of the temporary one-percentage-point reduction.
It was not particularly close.
The headline rate was better.
The overall financial outcome was worse.
To be clear, I am not suggesting that the broker was intentionally trying to give us bad advice. It is possible she had not fully considered how the restriction would affect our particular strategy.
But I had explained what we intended to do.
The recommendation focused on helping us obtain a mortgage. It did not fully account for what we planned to do after closing.
There was also an unavoidable conflict: if we selected another lender, she would not be compensated for the transaction.
That does not make her dishonest or the mortgage inherently bad. It simply means that her role, incentives and scope were different from those of someone we might hire specifically to evaluate the decision within our complete financial plan.
The retirement rollover that could have closed another door
The second recommendation came from a representative of a national bank.
After learning that I still had money in my former employer's 401(k), he suggested rolling it into an Individual Retirement Account (IRA) at the bank. He explained that an IRA would offer more investment choices and that moving the assets could qualify us for a relationship-based mortgage-rate discount.
Again, the offer sounded attractive.
But I use a strategy commonly called a backdoor Roth IRA. It involves making an after-tax contribution to a traditional IRA and then converting it to a Roth IRA.
The strategy becomes more complicated when someone has other pre-tax IRA money. Under what is commonly called the pro-rata rule, the Internal Revenue Service (IRS) generally looks at a person's combined traditional, SEP and SIMPLE IRA balances when determining how much of a Roth conversion is taxable.2
If I had rolled my large pre-tax 401(k) balance into an IRA, most of my future backdoor Roth conversions could have become taxable. The rollover would not have made the strategy impossible, but it could have made it substantially less tax-efficient and more difficult to manage.
A recommendation intended to give me "more investment options" could have complicated one of the useful planning tools already in my toolbox.
Once again, I do not believe the bank representative was trying to harm us. He may not have known that I used this strategy because he had never examined our complete financial picture.
He was explaining the benefits of his bank's products. But if we obtained the mortgage elsewhere, he would not receive credit for originating our loan.
That did not automatically make his recommendation wrong.
It meant that I needed to evaluate it in context.
A good product can still be wrong for you
Both professionals presented legitimate potential benefits:
· A temporary mortgage-rate reduction
· A credit toward a loan fee
· A relationship-based mortgage discount
· A broader selection of investments
The problem was not that those benefits were imaginary. The problem was that they were presented without fully considering how the decisions would affect the rest of our plan.
The mortgage offer did not adequately account for our planned principal payment and recast.
The rollover recommendation did not account for my backdoor Roth IRA strategy or the other differences between retaining an employer plan and moving the money into an IRA.
Each recommendation made sense through the lens of the product being offered.
Neither professional had been engaged to examine our entire financial picture.
What does it mean to work with a fiduciary
"Fiduciary" is a word that is used frequently in financial services, sometimes without much explanation.
In general, an investment adviser providing advisory services must act in the client's best interest and not place the adviser's interests ahead of the client's. Material conflicts of interest must also be disclosed.3
That does not mean a fiduciary will always be right - or that professionals who are paid through commissions are dishonest.
The difference is often the scope of the assignment.
A mortgage professional may be focused on helping you obtain a mortgage. A bank representative may explain the advantages of the bank's products. A fiduciary financial planner can be engaged to examine how a recommendation affects your taxes, investments, retirement accounts, liquidity and long-term goals. Of course, fiduciary advice has limits: it involves a fee, depends on complete information and cannot guarantee a better outcome.
The question is not simply whether the product has benefits.
It is whether those benefits still make sense when viewed as part of your complete financial plan.
Paying for advice can create a different relationship
Many people hesitate to pay directly for financial advice. I understand why: a planning fee is visible, while commissions, product expenses and lost planning opportunities can be much harder to see.
But not receiving a separate invoice does not tell you how the professional is compensated or what incentives may influence the recommendation.
A financial planner can be paid to evaluate the decision itself - not to complete a mortgage, rollover or product sale.
The value is not simply having someone else perform the arithmetic. It is having someone examine how the decision affects the rest of your financial life before you make a choice that may be difficult to reverse.
In our case, a few additional questions changed how we viewed two attractive offers.
The lower rate was not necessarily the better mortgage.
The larger investment menu was not necessarily the better retirement decision.
And the person offering the product was not necessarily the person best positioned to determine whether it fit our plan.
The most important question was not:
What benefits does this product offer?
It was:
What happens to the rest of my financial plan if I say yes?
Sources
1. Fannie Mae, Re-amortized Recast Mortgages
2. Internal Revenue Service, Instructions for Form 8606
3. U.S. Securities and Exchange Commission, Investor.gov, Investment Advisers
Disclosure
Investment advisory services offered through Fiduciary Financial Advisors a registered investment adviser. The views expressed represent the opinion of Fiduciary Financial Advisors. Information does not constitute investment, tax, or legal advice.
What Would You Gain and Give Up by Working One Day Less Per Week?
What would you gain by working one day less each week? For a physician earning $400,000, the trade-off could be $80,000 in annual income in exchange for 750 additional weekdays over 15 years. Is the extra time worth it?
Have you ever thought about working one day less per week?
Maybe you're a physician working five days a week and would love to move to four. More time with your kids. A regular day to exercise, run errands, travel, or simply have some breathing room.
Then you do the quick math.
If you earn $400,000 per year and reduce your schedule by 20%, your compensation could fall to roughly $320,000.
That's $80,000 a year.
And the idea quickly becomes: “I'd love to work less, but I can't afford to give up $80,000 every year.”
But you may not actually be giving up $80,000 of spendable income.
Start with where your $400,000 is going
Imagine you're 40 years old, married with two children, and earning $400,000 per year.
Like many physicians, you got a later start on saving because of medical school and residency. You have about $150,000 invested and still have $150,000 of student loans.
You're now earning a great income and making up for lost time.
You maximize your workplace retirement plan. Your employer contributes additional money toward retirement. You're paying $30,000 per year toward your student loans. You're putting $12,000 per year into 529 accounts. Your family spends about $150,000 per year. And whatever is left over goes into a brokerage account.
You're doing well.
But do you actually know how much of your income is going toward each of those things?
That becomes very important when you start thinking about working less.
An $80,000 pay cut doesn't mean $80,000 less to live on
If your income falls from $400,000 to $320,000, you won't necessarily take home $80,000 less. That's because some of that $80,000 would have gone to taxes.
For a simplified 2026 Pennsylvania example, assume this physician is married filing jointly, makes the maximum $24,500 pre-tax workplace retirement-plan contribution in either scenario, takes the standard deduction, and has no other income or deductions. Under those assumptions, the $80,000 reduction in gross compensation would reduce federal income tax, Pennsylvania income tax and Medicare tax by roughly $24,000. The reduction in after-tax cash flow would therefore be about $56,000, not the full $80,000. ¹²³
The actual result for any household could be materially different depending on filing status, deductions, other income, state and local taxes, benefits and other circumstances.
That's still a lot of money.
But now ask: Where does that $56,000 actually come from?
Your family doesn't necessarily have to spend $56,000 less.
Your mortgage doesn't change. You don't suddenly stop taking vacations or going out to dinner. You could potentially continue making the same student loan payments, funding your 529s and maximizing your retirement plan.
If you were previously investing $50,000 or more each year into a brokerage account, much of the impact might simply be that you invest less.
So your choice may not really be a $400,000 lifestyle versus a $320,000 lifestyle.
It may be closer to: work five days and save significantly more for the future, or work four days, maintain a similar lifestyle and accumulate wealth more slowly.
That's a very different decision.
But can you still retire?
This is where knowing whether you're actually on track becomes important.
You may have heard the term Monte Carlo analysis. The name makes it sound more complicated than it needs to be.
Think of it as a financial stress test.
Instead of assuming your investments earn exactly the same return every year, a Monte Carlo analysis runs a financial plan through many hypothetical market paths. The result is often expressed as a probability of success - the percentage of simulated scenarios in which the plan does not run out of money before the end of the planning period. In a household plan, that period commonly extends through the assumed lifetimes of both spouses.⁴
For example, a 90% probability of success means that the plan still had money remaining at the end of the modeled planning period in approximately 90% of the hypothetical scenarios. It does not mean there is exactly a 90% chance you will be fine, nor does it account for every adjustment you might make along the way. In real life, you may respond to changing circumstances by spending less, saving more, working longer or changing other goals. The result depends on the assumptions used and is not a prediction or guarantee.⁴
A 100% probability of success is not necessarily an appropriate target for a household. Someone with flexible spending, a willingness to work longer or goals that can be adjusted may be comfortable with a lower modeled probability than someone with less flexibility. Generally, the lower the modeled probability, the greater the likelihood that changes may be needed later to avoid running out of money. The appropriate range is individual and should be considered in the context of the assumptions and available trade-offs.
Suppose you're planning to retire at 55.
Working five days per week, your financial plan might show a 95% probability of success.
Then you model working four days per week while keeping most of your lifestyle the same.
Maybe it falls to 88%.
Those percentages are hypothetical and are included only to illustrate how the decision could be evaluated. An actual analysis could produce very different results.
That's a meaningful difference. But it doesn't necessarily mean you can't afford to work four days.
Now you have a much better question to consider: Is moving from a 95% modeled probability of success to 88% worth having an extra day every week for the next 15 years?
There isn't one correct answer.
What if working less meant working a little longer?
There's another way to look at the trade-off.
Maybe working five days per week gets you to your desired retirement at 55 with a 95% modeled probability of success. Working four days might get you to 55 with an 88% modeled probability.
But what happens if you work four days until 56? Or 57?
Perhaps working a couple of additional years gets your plan back near the same modeled probability of success. Or perhaps it takes longer. The answer depends on your actual financial circumstances.
Now the decision becomes much more interesting.
Imagine your choices were: work five days per week until 55, or work four days per week until 57.
Again, those ages are only an illustration. Your numbers could look completely different.
But consider what you received in exchange for those additional two years at the end.
Working one fewer day per week for 15 years gives you approximately 50 additional weekdays per year.
That's about 750 additional weekdays between ages 40 and 55.
And those 750 days happen now
That's the part a spreadsheet has difficulty measuring.
Those days happen while your kids are still living at home.
They're Fridays when you're 42, not Tuesdays when you're 72.
Maybe you coach your child's soccer team. Take a long weekend with your family. Exercise more. Have lunch with your spouse. Visit your parents. Pursue something you've always wanted to do.
Or maybe you just have a day when nobody needs anything from you.
Those experiences can also produce what I like to think of as memory dividends. The value of a great experience doesn't necessarily end when the experience is over. You may continue enjoying the memories for decades.
We spend a lot of time thinking about how money compounds.
It's worth remembering that experiences can compound too.
You need to know your numbers first
I'm not suggesting that every physician should work four days per week.
If you're 40, haven't saved much yet, have substantial student debt and are spending most of what you earn, the numbers might tell you that reducing your income right now would significantly compromise your goals.
Maybe the answer is not yet.
Perhaps you spend the next three years paying down debt and building your investments, and then revisit the question.
But you won't know until you understand two things:
Where is my money going?
And: Am I on track?
You might discover that working less would require major lifestyle changes or significantly delay financial independence.
Or you might discover that instead of working five days a week to move your modeled probability of success from 88% to 95%, you'd rather accept a little less financial certainty in exchange for hundreds of additional days during an important period of your life.
While I used a physician earning $400,000 in this example, the underlying idea isn't limited to high earners. The numbers and available choices will obviously look very different for someone earning $65,000, and reducing income may require much more significant trade-offs. But the same questions still apply: Where is my money going? Am I on track? And could changes to my spending, saving, or timeline give me more flexibility? Financial independence isn't reserved for people with exceptionally high incomes - the path just looks different for everyone.
Financial planning shouldn't only tell you whether you'll have enough money someday.
It should help you understand what choices your money gives you today.
Sources
¹ IRS, 2026 federal income-tax brackets and standard deduction: https://www.irs.gov/newsroom/irs-releases-tax-inflation-adjustments-for-tax-year-2026-including-amendments-from-the-one-big-beautiful-bill
² IRS, 2026 workplace retirement-plan contribution limits: https://www.irs.gov/newsroom/401k-limit-increases-to-24500-for-2026-ira-limit-increases-to-7500
³ Pennsylvania Department of Revenue, personal income-tax rate: https://www.pa.gov/agencies/revenue/resources/tax-types-and-information/personal-income-tax
⁴ Charles Schwab, Retirement Income Calculator Methodology: https://www.schwab.com/retirement-income-how-it-works
Investment advisory services offered through Fiduciary Financial Advisors a registered investment adviser. The views expressed represent the opinion of Fiduciary Financial Advisors. Information does not constitute investment, tax, or legal advice.