You Do Not Necessarily Need an Advisor to Manage Your Investments
You may not need an advisor to select investments. Guido Jaramillo shares an early investing mistake and explains where broader financial planning can still add value.
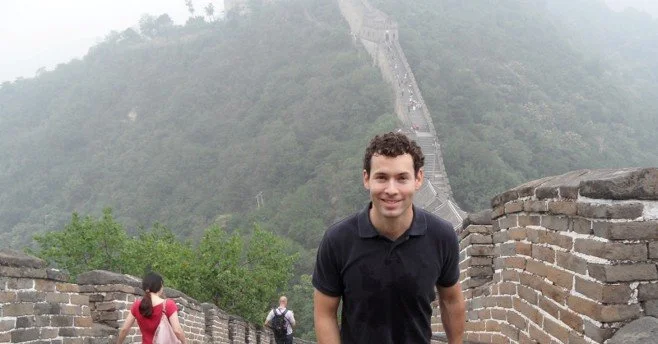
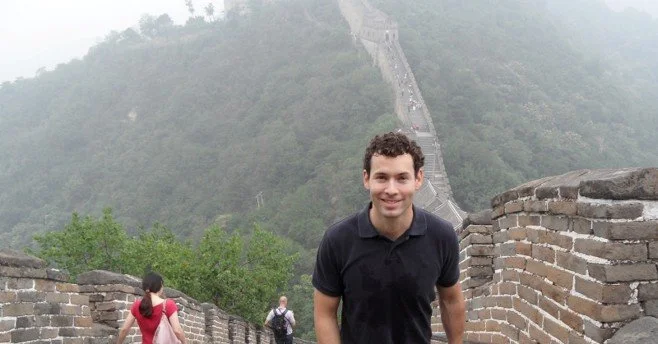
At the Great Wall of China, during the period when I first began investing outside my 401(k).
Some of my financial-planning friends may not like me saying this:
You do not necessarily need an advisor to manage your investments.
A disciplined investor can build a broadly diversified portfolio using a small number of inexpensive funds.¹ ²
If you save consistently, avoid unnecessary trading and remain invested through difficult markets, you may not need to pay someone to select investments for you.
Of course, knowing what to do and consistently doing it are not always the same thing.
The photograph accompanying this article was taken at the Great Wall of China during a period when my career was going well and I was fortunate to be traveling around the world.
I was contributing to my 401(k), living below my means and, for the first time, accumulating enough savings to invest meaningful money outside my retirement account.
I felt successful and increasingly confident about managing my financial life. Some of that confidence was justified. But some of it became overconfidence—and influenced how I invested.
I wanted to beat the market
Around 2013 or 2014, my dad recommended that I invest the money in diversified index funds. But the market was near an all-time high, and I worried that if it declined, my investments would fall with it.
I thought I could do better.
I researched companies and selected approximately six to eight individual stocks. I placed considerable weight on whether I liked the companies' management teams. Looking back, I was overconfident in my ability to identify which companies would outperform.
Over time, I noticed a problem with my behavior. I was quick to sell investments after they had gained value, but reluctant to sell the investments that had declined because I kept expecting them to recover.
I sold my winners and held on to my losers.
I wanted to lock in my gains, while convincing myself that the investments that had declined would eventually recover.
Eventually, I stopped selecting individual stocks and moved the portfolio into broadly diversified index funds.
I used the realized losses to offset capital gains elsewhere in my portfolio, which reduced the tax impact of the transition.3
I never reconstructed the exact returns, so I cannot say precisely how my results compared with a diversified index fund. What I learned was that my approach left me concentrated, reactive and more confident than my experience justified.
Fortunately, the mistake was not catastrophic. I learned an important lesson relatively early in my investing life: Investment knowledge matters, but behavior matters too.
What mattered more than picking stocks
The most important financial decision I made was not selecting the right investments. It was consistently creating a gap between what I earned and what I spent—and investing the difference.
From my first day at Johnson & Johnson, I contributed enough to my 401(k) to receive the full employer contribution. I increased my contributions over time and generally lived below my means.
Looking back, I could have increased my contributions sooner. But starting early, consistently saving and avoiding lifestyle inflation mattered far more to my early progress than finding the perfect stock.
Not everyone has the same ability to save, particularly when income is limited or essential expenses are high. But for me, increasing the amount I invested was more valuable than trying to squeeze a slightly higher return from the portfolio.
Investment management is not financial planning
Professional advice may become more valuable when the questions extend beyond which investments to buy.
• How much should you save?
• Should you contribute to a traditional or Roth retirement account?
• How should taxes affect when you sell an investment or withdraw from an account?
• Can you afford to buy a home, reduce your work schedule or retire earlier?
• Are your investments coordinated with your cash needs, insurance coverage, estate plan and long-term goals?
Those are financial-planning questions, not simply investment questions.
An advisor may also help identify blind spots, evaluate tradeoffs and provide perspective when emotions are affecting an important decision. That does not guarantee a better outcome, and professional advice involves a cost. Its value depends on your circumstances and the quality and scope of the advice.
So do you need an advisor
Maybe not.
If your financial life is relatively straightforward, you are comfortable making decisions independently and you can remain disciplined through difficult markets, managing your own investments may be entirely reasonable.
You may not need someone to pick investments for you.
But you may benefit from someone who can help you understand how the different parts of your financial life fit together—and challenge your thinking before a reasonable-sounding decision becomes an expensive mistake.
Looking back, I did not need someone to help me find better stocks.
I needed someone to ask why I thought I could consistently choose the winners.
Sometimes the most valuable financial advice is not a new investment. It is a better question.
Sources
1. U.S. Securities and Exchange Commission, Investor.gov, Beginners' Guide to Asset Allocation, Diversification and Rebalancing
2. U.S. Securities and Exchange Commission, Investor.gov, Index Funds
3. Internal Revenue Service, Topic No. 409, Capital Gains and Losses
Disclosure
Investment advisory services offered through Fiduciary Financial Advisors a registered investment adviser. The views expressed represent the opinion of Fiduciary Financial Advisors. Information does not constitute investment, tax, or legal advice.
Financial Planning Insights
I enjoy exploring how financial decisions connect to the bigger picture—our careers, families, time, and the lives we want to build. Here are some of my recent articles on investing, financial planning, and making thoughtful trade-offs.



What Planting 42 Trees Taught Me About Financial Planning
Planting 42 trees reminded me that financial planning is rarely urgent—but waiting has a cost. The work happens today, while many of the benefits may not arrive for years.
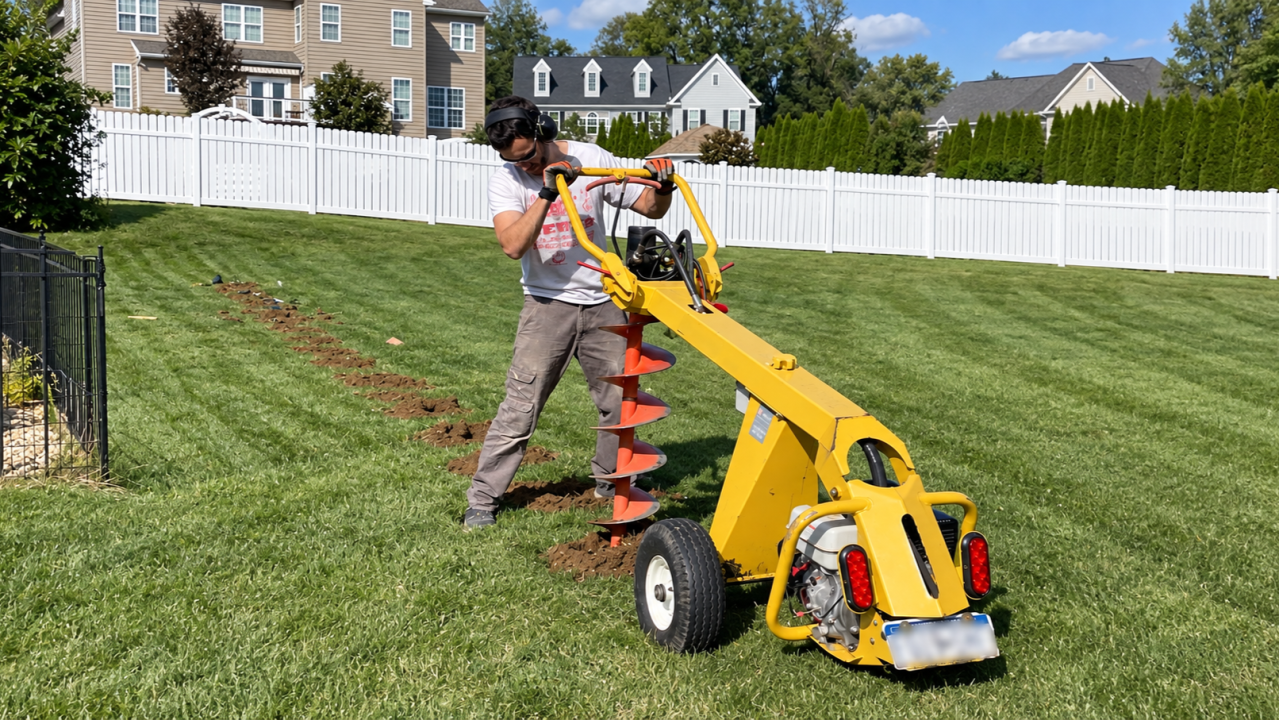
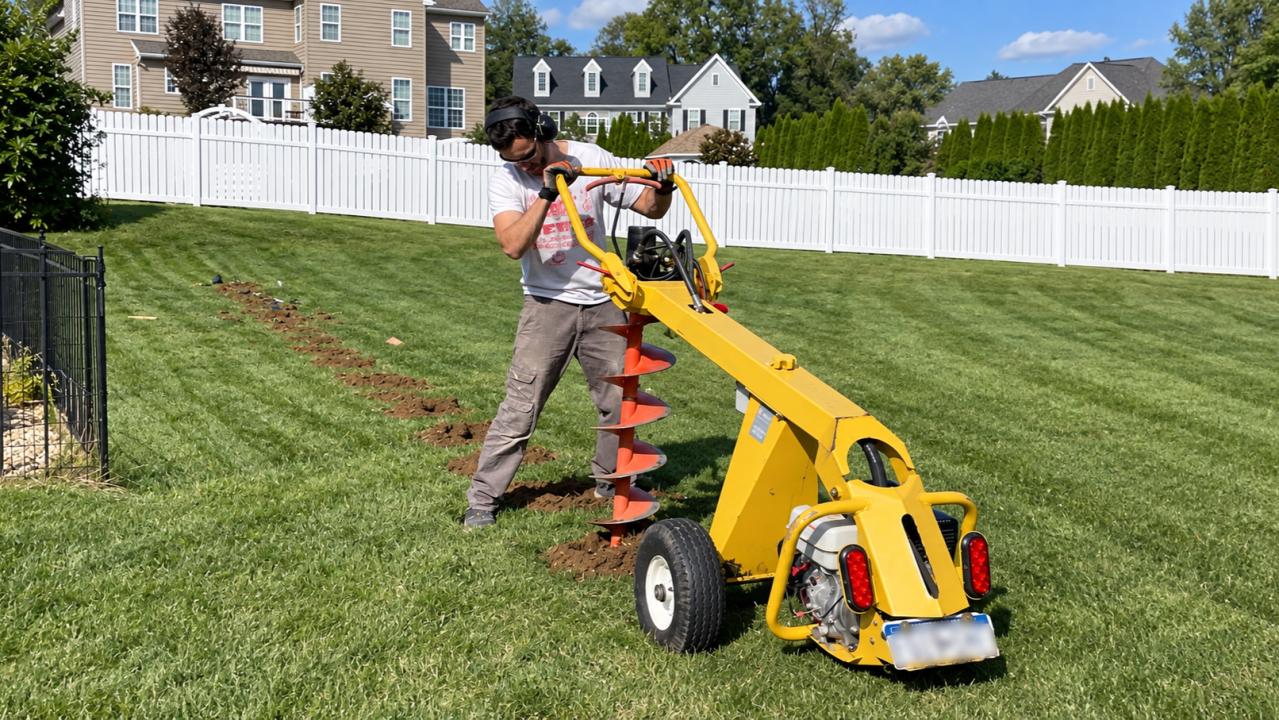
Planting one of the 42 trees that will eventually bring more shade and privacy to our backyard.
Earlier this summer, my family moved into a new house.
Like many homes in newer developments, the house sits on land that was largely cleared when the neighborhood was built. The previous owners planted a couple of trees, but most of the property was still fairly open.
We wanted more shade, privacy and a backyard that felt less like an open lot. Soon after moving in, we planted approximately 42 trees.
The work is finished. The trees are in the ground, the equipment has been returned and the yard has been cleaned up.
But the backyard we are picturing may still take years to develop.
There is a familiar saying:
The best time to plant a tree was 20 years ago. The second-best time is today.
After completing this project, I realized how much planting trees has in common with financial planning.
Nothing about it was urgent
We did not need to plant the trees this year.
There was no broken pipe or dead appliance forcing us to act. We could easily have postponed the project until next spring—or the year after that.
That is what makes long-term projects so easy to delay. The work and expense happen now. Most of the benefit arrives later.
Financial planning often feels the same way. If the bills are being paid and there is money in the bank, developing a plan may not feel urgent. Increasing retirement contributions, reviewing insurance or organizing an estate plan may not solve a visible problem today.
It is easy to say you will address it when work becomes less busy, the kids get older or your finances become more complicated.
But waiting gives both the trees and your money less time to grow.
Before digging I needed a plan
My original thought was simple: buy some trees and plant them along the edge of the yard.
It became more complicated very quickly.
I spent hours measuring the yard and marking our property boundaries. We also have a stormwater-management area and related restrictions that affect where we can plant. I called 811 to identify underground utilities and considered drainage, sunlight, existing structures and the space each tree would eventually need.
Because we were planting 42 trees, I also rented professional equipment rather than trying to dig every hole by hand.
Financial planning begins with a similar effort to understand the landscape.
Before deciding what to invest in or how much you can afford to save, you need to understand your cash flow, assets, debts, taxes, insurance, employee benefits and existing commitments.
You also need to know what you are trying to accomplish. Otherwise, you may take action—but not necessarily in the right place.
The right choice depended on the location
We researched which trees would grow well in our region, how tall and wide they would become, how quickly they would grow and how resistant they were to deer.
Along one narrow boundary, we planted Taylor junipers because their mature width should fit the available space. Where we had more room, we planted wider Spartan junipers that should eventually provide a fuller screen.
Neither tree was universally “better.” Each had a different job.
Financial decisions work the same way.
Money in an emergency fund has a different job from money invested for retirement decades from now. Different accounts and investments come with different benefits, risks and limitations.
The question should not simply be, “What is the best investment?”
A better question is, “What am I trying to accomplish, when will I need the money and what risks or limitations can I accept?”
Planning did not eliminate uncertainty
We researched the trees, measured the property, marked the locations and used the right equipment.
That does not guarantee every tree will thrive.
Weather, soil conditions, animals and our own mistakes can affect the outcome. Some trees may grow faster than expected. Others may struggle or need to be replaced.
Investing also involves uncertainty. Starting early does not guarantee a particular return, and investments can lose value. Planning cannot predict every market decline, tax change or unexpected expense.
The purpose of planning is not to eliminate uncertainty. It is to make informed decisions, identify risks and leave yourself enough time and flexibility to adjust.
Planting was also only the beginning. The trees will need water and periodic attention. A financial plan requires similar maintenance as your income, family, priorities and circumstances change.
We planted for the family we will be
After all that work, our backyard mostly looks like a yard with 42 small trees.
But beneath the surface, roots are developing. Each growing season should build on the one before it.
Investing can feel equally unrewarding at the beginning. Early contributions may appear small relative to the goal, and markets will not move upward consistently.
But time matters. Beginning earlier gives regular contributions and potential compounding more time to work.¹ It does not guarantee success, but postponing the decision sacrifices time that cannot be recovered.
We planted these trees for summer evenings several years from now, for the view from a patio we have not built yet and for the privacy we will appreciate as our children get older.
That is also what good financial planning asks us to do: make thoughtful choices that serve both the life we are living today and the life we hope to have later.
You may wish you had started years ago.
Most of us do.
But whether you are planting trees, creating a financial plan or making your first investment, the more useful question is not when you should have started.
It is what you can plant today.
Sources
¹ U.S. Securities and Exchange Commission, Investor.gov, “Build Wealth Over Time Through Saving and Investing”: https://www.investor.gov/build-wealth-over-time-through-saving-and-investing
Investment advisory services offered through Fiduciary Financial Advisors a registered investment adviser. The views expressed represent the opinion of Fiduciary Financial Advisors. Information does not constitute investment, tax, or legal advice.
This material is provided for informational and educational purposes only and should not be construed as individualized investment, tax, legal, or financial advice. Financial planning recommendations and strategies depend on each individual’s circumstances, objectives, risk tolerance, and other relevant factors. There is no guarantee that any financial planning strategy will achieve its intended results. Investing involves risk, including the possible loss of principal. Past performance is not indicative of future results. You should consult with appropriate financial, tax, and legal professionals regarding your individual circumstances before implementing any strategy discussed.
Financial Planning Insights
I enjoy exploring how financial decisions connect to the bigger picture—our careers, families, time, and the lives we want to build. Here are some of my recent articles on investing, financial planning, and making thoughtful trade-offs.